What makes car insurance comparison important for young adults?
Choosing suitable car insurance can be challenging for young drivers because premiums often depend on driving experience, age, location, vehicle type, and insurance history. Understanding these factors helps motorists identify Best Car Insurance For Young Adults options that balance affordability with meaningful financial protection. Rather than selecting the first available policy, young adults can compare coverage limits, deductibles, exclusions, and additional benefits to make informed decisions. A structured comparison also helps prevent unexpected expenses after an accident.
Why do young drivers often pay higher insurance premiums?
Insurance companies generally evaluate risk when calculating premiums. Drivers with limited experience may face higher rates because insurers have less evidence of their long-term driving behavior. Accident history, traffic violations, vehicle repair costs, and local claim patterns can also influence pricing.
Industry research consistently identifies age and driving experience as important rating factors, although their effects vary by state and insurer. Young adults can potentially improve their insurance profile by maintaining a clean driving record, avoiding unnecessary claims, and exploring eligible safe-driving discounts.
Which policy types should young adults compare?
The main options include liability, collision, and comprehensive coverage. Liability insurance generally covers qualifying injuries or property damage caused to others, subject to policy terms and limits. Collision coverage helps pay for damage to the insured vehicle following a covered collision, while comprehensive coverage addresses certain non-collision events, such as theft, hail, vandalism, or falling objects.
Minimum required coverage may satisfy legal obligations, but it might not provide sufficient financial protection for every driver. Comparing broader policies helps young motorists understand the difference between basic legal compliance and coverage suited to their circumstances.
How much should young adults expect to pay?
There is no universal premium for young drivers. Costs vary according to age, state, vehicle, driving record, annual mileage, selected limits, and deductible. Two people of the same age can receive substantially different quotes because their risk profiles differ.
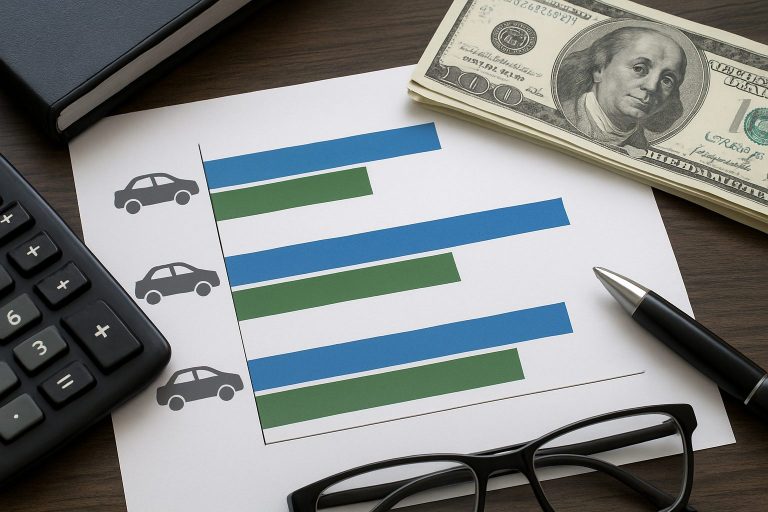
Young adults should request multiple quotes using identical coverage limits and deductibles. This creates a more meaningful comparison than choosing whichever advertised price appears lowest. Monthly payments should also be evaluated alongside the total annual premium, applicable fees, and available payment arrangements.
Which discounts can make coverage more affordable?
Insurers may offer discounts for safe driving, qualifying driver education, low mileage, eligible vehicle safety features, or bundling certain policies. Students who meet specific academic requirements may also qualify for discounts under some programs.
Availability and eligibility differ among insurers and locations. Young adults should ask which discounts apply, what documentation is necessary, and whether a discount continues at renewal. Telematics programs may reward certain driving habits, although participants should review data collection practices and program conditions before enrolling.
How do deductibles influence the overall cost?
A deductible represents the amount a policyholder generally pays toward a covered claim before the insurer contributes. Choosing a higher deductible can reduce premiums, but it increases the amount required after a qualifying loss.
Young adults should consider their emergency savings before selecting a deductible. A lower monthly payment may not be worthwhile if an unexpected repair bill becomes difficult to manage. Comparing several deductible levels can reveal a practical balance between immediate affordability and future financial responsibility.
What should drivers examine before purchasing a policy?
Review exclusions, coverage limits, claim procedures, rental reimbursement options, roadside assistance, and cancellation conditions. Drivers financing or leasing vehicles should also check lender requirements, which may include collision and comprehensive coverage.
Ultimately, comparing insurance involves more than finding the cheapest quotation. Young adults benefit most from policies that offer appropriate protection, manageable deductibles, transparent conditions, and dependable claims support. Reviewing coverage annually helps ensure the policy remains aligned with changing budgets, vehicles, and driving habits.
Key Takeaways
- Car insurance premiums for young drivers depend on factors such as driving experience, age, location, vehicle type, and insurance history.
- Young adults can improve their insurance profile by maintaining a clean driving record, avoiding unnecessary claims, and exploring safe-driving discounts.
- The main policy types young adults should compare are liability, collision, and comprehensive coverage, each serving different protection needs.
- Insurance costs can vary significantly even among individuals of the same age due to differences in risk profiles, state regulations, and driving records.
- Available discounts for car insurance may include those for safe driving, qualifying driver education, or low mileage, but eligibility varies by insurer.
- Before purchasing a policy, drivers should examine exclusions, coverage limits, and claims procedures to ensure comprehensive understanding of the policy.
About the Author